
New York Auto Insurance for New Drivers
New York auto insurance for new drivers is a household-placement and policy-comparison problem, not simply a search for the lowest monthly payment. New York new driver insurance should identify the real driver, vehicle, principal operator and garaging location, then keep the New York coverage baseline unchanged while carriers are compared. This guide separates permit-holder treatment, newly licensed experience, parent-versus-standalone placement, ZIP-based rating inputs, brand fit and final policy activation.
Enter the ZIP where the vehicle is normally garaged. For New York new driver auto insurance quotes, keep household operators, vehicle assignment, liability limits, No-Fault, UM or SUM, collision and comprehensive deductibles, annual mileage, policy term and effective date consistent across carriers.
QuotesAutoInsurance.org is independently operated and is not a government agency or insurance company. The form may connect users with licensed insurance providers or partners and does not guarantee a policy, insurer, approval, discount or price.
How New York Auto Insurance for New Drivers Works
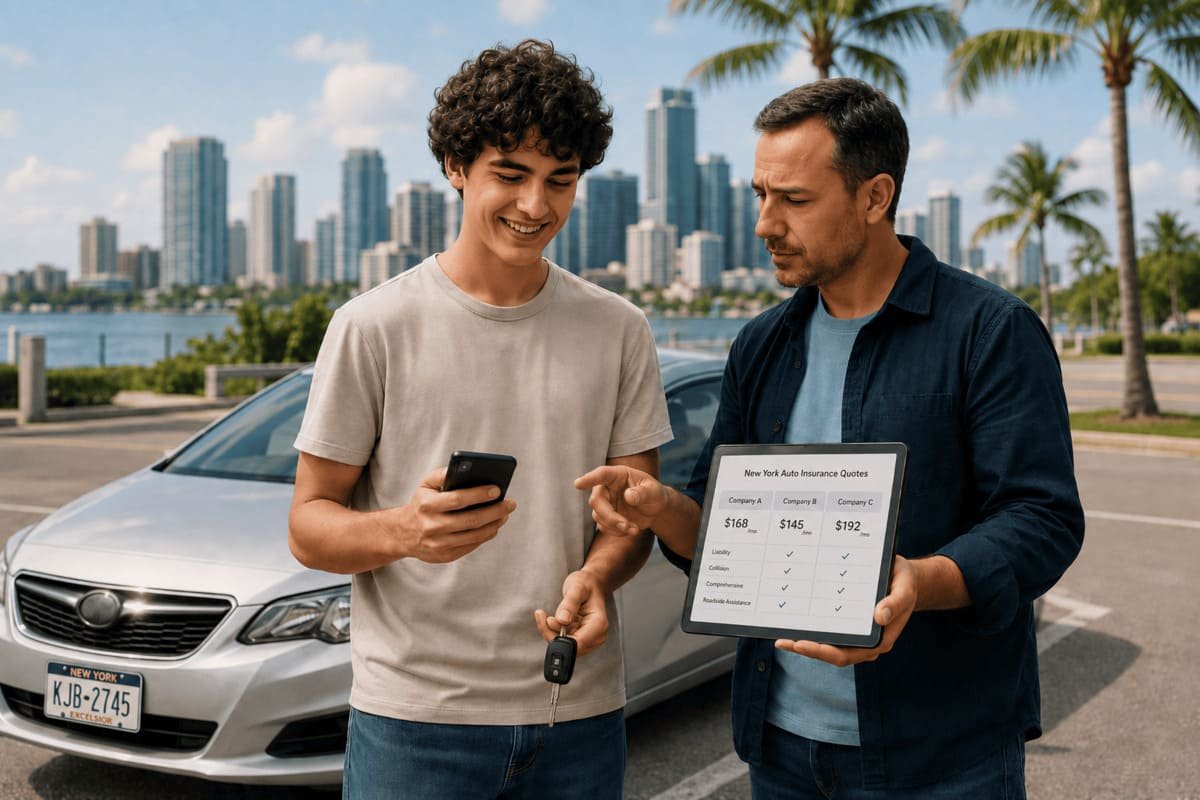
New York car insurance for new drivers includes several different situations: a teenager practicing with a permit, a newly licensed household member, an adult getting a first license, a college-age driver still living at home, or an independent driver buying a first vehicle. That is why New York newly licensed driver insurance should be built around the actual household and vehicle facts rather than age alone.
The broader New York auto insurance quotes by ZIP page covers statewide shopping. This page has a narrower job: decide where the new driver belongs, establish the policy baseline, and then compare New York new driver insurance without changing the inputs that created the rate.
There is no universal best car insurance for new drivers in New York. The strongest result is the written policy that fits the real operator and vehicle, carries the intended protection, remains affordable after deductibles and installments, and can be activated without a lapse.
Step 1: Classify the New Driver Before Comparing Rates
Before comparing carriers, identify the driver’s actual status and how the household will use the vehicle. Rating, disclosure and vehicle-assignment decisions can change when a learner permit becomes a license or when a new operator becomes the principal driver.
New York learner permit insurance deserves its own checkpoint. New York DFS explains that most insurers consider a household member with a learner permit to be an insured operator for rating because the permit creates additional exposure. New York learner permit car insurance therefore should not be handled by assuming that practice driving is invisible to the insurer.
For New York permit holder insurance, contact the carrier before regular practice begins and again when the permit holder becomes licensed. Confirm when the person must be disclosed, listed or rated, which vehicle is assigned, and when any classification change becomes effective.
New York inexperienced driver insurance is broader than teen insurance. DFS states that a principal operator licensed for less than three years at the start of the policy period receives a New York inexperienced operator surcharge regardless of age. An adult first-time driver can therefore face the same licensed-experience issue even without the age profile of New York teen driver insurance.
New York young driver insurance may involve both age and limited experience, while an older first-time driver may primarily be affected by licensed experience, vehicle assignment and household structure. That distinction keeps the page focused on the insurance classification that actually applies.
New York learner permit restrictions operate separately from insurance rating. A permit holder generally needs a supervising driver age 21 or older with a valid license for the vehicle, and additional rules apply by region. New driver insurance in New York City, new driver insurance on Long Island and new driver insurance in upstate New York can therefore involve different driving-permission questions even when the insurance policy is otherwise similar.
The permit restriction question is not a substitute for the insurance question. The DMV rules decide when and where the permit holder may drive; the insurer decides how the household operator must be disclosed, assigned and rated under the policy.
Step 2: Choose Household Placement and Vehicle Assignment
Once the driver status is clear, decide where the person belongs on the policy and which vehicle is assigned. Keep ownership, residence, registration, garaging and actual use aligned before comparing price.
A New York parent policy can be efficient when the new driver lives in the household and regularly uses family vehicles. It can preserve one set of declarations, billing and claim contacts and may preserve an applicable New York multi-car discount, but the carrier still needs accurate operator and vehicle information.
A separate new driver policy in New York can make sense when the driver owns and registers a vehicle independently, lives at a different address, or otherwise qualifies for a standalone structure. The standalone option should reflect the true residence, ownership, garaging location and vehicle use rather than being used to avoid a household-driver classification.
New York household driver insurance and New York resident operator insurance both point to the same practical issue: every person with regular access to the vehicle should be disclosed as required by the insurer. The quote should show who is a named insured, who is a listed operator and which person is treated as principal operator.
New York principal operator insurance matters because the rate can change depending on which driver is assigned as the main operator of a particular vehicle. New York vehicle assignment insurance is therefore a real comparison variable; do not compare a quote that assigns the new driver to one car with another quote that assigns that driver to a different car and call the price difference a carrier saving.
New York first car insurance should use the vehicle that will actually be owned, registered and driven. For insurance for a first car in New York, compare VIN, trim, safety equipment, financing, annual mileage, commute, other use and the driver assigned to the vehicle.
The New York garaging ZIP should reflect where the vehicle is normally kept. New York auto insurance quotes by ZIP can change because insurers use approved rating approaches and territory-related information, so a mailing address should not replace the actual garaging location merely to alter a quote.
A New York new driver declarations page is the best final record for checking the named insured, drivers, vehicles, limits, deductibles, endorsements, discounts and policy period. The New York new driver policy effective date should be confirmed before prior required coverage is canceled.
Step 3: Lock the New York Coverage Baseline
Next, freeze the New York protection baseline. Compare carriers only after the required liability, No-Fault and uninsured-motorist layers, plus any selected physical-damage or SUM protection, are set the same way.
New York DMV insurance requirements start with New York State-issued automobile liability insurance for a New York-registered vehicle. New York minimum auto insurance for most vehicles includes at least $25,000 bodily injury to one person, $50,000 bodily injury to two or more people, $10,000 property damage per crash, and separate $50,000/$100,000 death limits.
New York 25/50/10 insurance is useful shorthand, but New York minimum car insurance is not only liability. New York $50,000 PIP is the basic No-Fault layer, and New York uninsured motorist coverage is also part of the required protection for qualifying New York accidents.
New York no-fault insurance can address qualifying medical expenses, lost earnings and certain other necessary expenses subject to the policy and regulatory rules. New York liability insurance for new drivers should be compared at the same limits across every carrier so that the apparent savings do not come from weaker liability protection.
The separate New York auto insurance laws page explains the compliance layer in more depth, including required limits, No-Fault deadlines, UM/SUM and continuous insurance.
New York collision coverage and New York comprehensive coverage are not ordinary state registration minimums, but a lender or lease can require physical-damage protection. New York full coverage for new drivers usually means a practical package that combines the state-required protections with collision and comprehensive, not a single standardized legal product.
New York SUM coverage is a separate decision involving supplementary uninsured and underinsured motorist protection. Keep the SUM selection and bodily-injury limits consistent when comparing carriers; otherwise one quote may appear cheaper because it contains materially less protection.
Drivers comparing affordable full coverage auto insurance should match collision and comprehensive deductibles, rental, roadside and any endorsements. New York full coverage insurance quotes are meaningful only when those settings remain equivalent.
Step 4: Build the New-Driver Rate and Discount Baseline
With placement and coverage fixed, build the price baseline. Compare the same licensed experience, vehicle use, garaging territory, limits, deductibles and confirmed discounts before attributing a rate difference to the insurer.
New York new driver insurance cost can vary with licensed experience, age classification, driving record, prior coverage, household operators, principal-operator assignment, vehicle, annual mileage, use, territory, selected limits, deductibles and insurer-specific rating rules. New York new driver insurance rates should therefore be compared from written offers generated from the same facts.
License date, accidents, violations, prior coverage and the driver’s classification can affect the quote.
Resident operators, parent-policy placement, standalone ownership and principal-operator assignment should match reality.
VIN, vehicle type, safety equipment, financing, mileage, use and real garaging territory belong in every comparison.
Liability, PIP, UM or SUM, physical damage, deductibles, endorsements and effective date should stay consistent.
Cheap car insurance for new drivers in New York should mean the lowest suitable written price among equivalent offers, not the lowest number produced by removing a driver or coverage. Affordable car insurance for new drivers in New York also has to account for the deductible and total policy-term payment structure.
New York new driver insurance discounts can include insurer-specific savings and discounts recognized or required under state rules. A New York good student discount may be available from insurers to qualifying youthful operators, while eligibility and documentation vary by company.
A New York accident prevention course discount can apply when the principal operator completes a qualifying approved course. State guidance also identifies statutory discounts connected with specified safety or anti-theft equipment. Always verify that every eligible credit actually appears in the policy rating information.
The New York auto insurance discounts page provides a broader checklist for comparing credits without changing the underlying policy protection.
Step 5: Compare Carrier Fit Without Changing the Baseline
Brand comparison comes after the household and policy baseline is fixed. Progressive, GEICO, Allstate and other carriers should be tested against the same inputs so carrier fit, not a changed application, explains the result.
Progressive insurance for new drivers in New York should be evaluated with the same household structure and vehicle assignment used elsewhere. The Progressive insurance quotes page can be used for a separate brand review after the New York baseline is fixed.
GEICO insurance for new drivers in New York should be compared the same way. The site’s GEICO coverage for new drivers guide focuses on the new-driver coverage question rather than changing the state baseline.
For households also comparing brand-level auto and property options, the separate GEICO insurance quotes guide reviews GEICO auto and homeowners quote structures by ZIP. Keep the New York auto policy comparison independent first, because the issuing companies, underwriting and policy terms for auto and homeowners coverage can differ.
Allstate insurance for new drivers in New York belongs in the same controlled comparison. Review Allstate insurance quotes using the same drivers, vehicle, ZIP, limits, deductibles and policy dates rather than a looser brand-to-brand price comparison.
New York new driver insurance companies can differ in underwriting appetite, discounts, billing, digital tools, claims handling and renewal treatment. New York auto insurance companies for new drivers should therefore be compared from the actual written offers available to that household.
Step 6: Compare Quotes and Activate the Policy Correctly
The final step is quote control and activation. Keep the same application facts through underwriting, then verify the issued policy, effective date and proof before ending existing coverage.
| Checkpoint | Keep this identical across quotes |
|---|---|
| Drivers | Named insured, resident operators, permit holders, license dates, accidents, violations and prior coverage |
| Vehicle | VIN, trim, ownership, financing, principal operator, mileage, commute and other use |
| Location | Real New York garaging ZIP and registration information |
| Required protection | Liability, basic No-Fault and uninsured motorist settings |
| Optional protection | Higher liability, SUM, additional PIP, collision, comprehensive, rental, roadside and endorsements |
| Cost | Total policy-term premium, down payment, installments, fees, deductibles and discounts |
| Timing | Policy term, effective date, proof of insurance and cancellation date of prior coverage |
To compare New York auto insurance quotes fairly, save one complete baseline and change only the carrier. New York new driver car insurance quotes should use the same drivers, vehicle, coverage and timing so the final premium difference reflects the carrier’s offer rather than altered inputs.
New York auto insurance quotes for new drivers and New York insurance quotes for new drivers should be treated as preliminary until underwriting and policy issuance are complete. A quote screen is not the same thing as an issued declarations page.
A New York insurance ID card is part of the state proof process, and New York continuous coverage matters while the registration remains valid. Confirm the replacement policy is issued and effective before the existing required insurance ends.
After an accident, use the New York auto insurance claim page for the reporting workflow. New-driver status does not remove the separate policy duties or New York No-Fault timing rules that can apply to a claim.
New York Auto Insurance for New Drivers FAQ
New York requires the vehicle’s policy to meet the state insurance rules that apply to the registration. For most private passenger vehicles, the baseline includes bodily-injury and property-damage liability, basic No-Fault or PIP, and uninsured-motorist bodily-injury protection. Collision and comprehensive are not state registration minimums, although a lender or lease can require them.
Do not assume a resident permit holder can be ignored. New York DFS says most insurers consider a household member with a learner permit an insured operator for rating because the permit creates additional driving exposure. Ask the insurer when the permit holder must be disclosed, listed, assigned to a vehicle, or rated.
New York DFS states that a principal operator licensed for less than three years at the start of the policy period receives an inexperienced-operator surcharge regardless of age. That means the new-driver issue is not limited to teenagers; an adult who is newly licensed can also fall into the inexperienced-driver classification.
Sometimes, but there is no universal answer. A household policy can preserve multi-car or multi-policy discounts and may spread vehicle assignments differently, while a standalone policy can price ownership and use separately. Compare both structures with the same drivers, vehicles, limits, garaging ZIP, deductibles, and effective date.
Use accurate household and vehicle information, compare the same coverage across several insurers, verify good-student or other eligible discounts, check whether an approved accident-prevention course helps, review vehicle assignment, and choose deductibles that remain affordable after a claim. Do not create a lower quote by omitting a resident driver or changing the real garaging address.
No. A lower price can reflect lower liability limits, higher deductibles, missing collision or comprehensive coverage, reduced supplementary uninsured or underinsured motorist protection, different vehicle assignment, or a different payment structure. Compare the declarations and total policy-term cost, not only the first payment.
Use one carrier-neutral baseline. Enter the same household operators, vehicle, principal operator, real garaging ZIP, annual mileage, use, liability limits, PIP, UM or SUM choice, collision and comprehensive deductibles, and effective date. Then compare the written offers and insurer-specific discounts rather than assuming one brand is always cheapest.
Yes, when the ownership, registration, residence, vehicle use, and insurer eligibility support that setup. A separate policy can make sense for a driver who owns and registers a vehicle independently, but it should not be used to hide a household operator, alter the real garaging location, or create a coverage gap.
Confirm the replacement policy has actually been issued, the required payment has been accepted, the effective date is correct, the New York insurance proof is available, and the DMV insurance information can match the registration. Avoid canceling the existing required coverage based only on a quote or unfinished application.
Yes. New York has statewide learner-permit supervision rules and additional regional restrictions. New York City, Long Island, and upstate New York can differ in where and when junior permit holders may drive, so a new driver should check the current DMV rules for the area where practice driving will occur.
Bottom line: New York new driver insurance works best as a controlled placement-and-carrier process. Classify the driver, choose the legitimate household or standalone structure, assign the real vehicle and garaging ZIP, lock the New York coverage baseline, verify discounts, compare equivalent carrier offers, and activate the replacement policy before canceling existing required coverage.