
What Affects Liberty Mutual Insurance Rates? Quote Price Factors
Liberty Mutual quote price factors are easiest to understand when you audit the quote in layers instead of changing several settings at once. A Liberty Mutual quote price can move because of the driver, vehicle, annual mileage, ZIP code, credit-related insurance information where permitted, claims, coverage limits, deductibles, discounts, or home replacement-cost details. The goal of this page is to explain why the price changes, not merely how to make the displayed number smaller.
Save one quote you would actually buy. Keep the same garaging ZIP, drivers, vehicle, annual mileage, liability limits, collision and comprehensive choices, deductibles, effective date, and payment setup. For home insurance, also lock the property address, dwelling amount, construction details, roof information, and deductible type. Then test one change at a time.
Compare auto pricing only after the driver, vehicle, mileage, limits, and deductibles are matched.
Use the actual garaging ZIP and the coverage you would realistically keep.
Keep rebuild assumptions, property details, limits, and deductibles stable before comparing home prices.
A different dwelling amount or deductible can make a cheaper quote look more attractive than it really is.
Liberty Mutual Quote Price Factors for Auto and Home Insurance
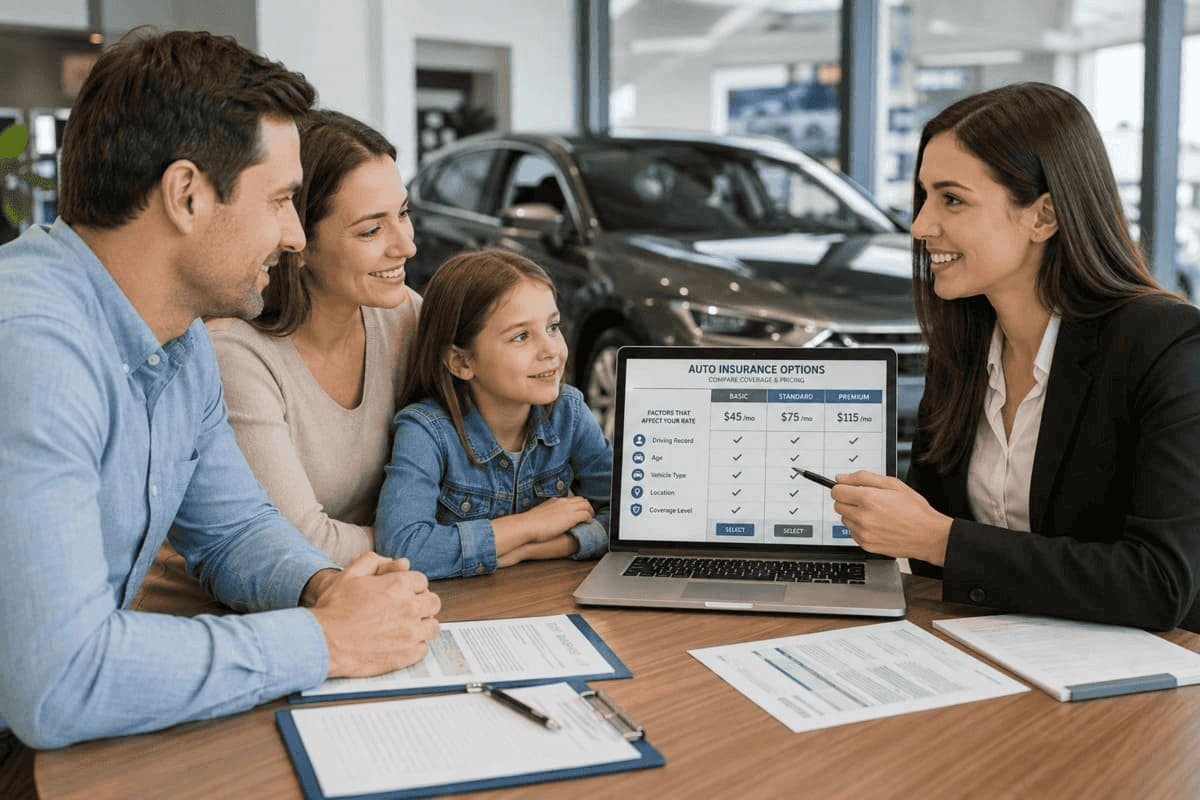
Liberty Mutual insurance quote factors are not limited to one visible score. The company currently says car insurance costs can vary based on location, driving history, mileage, vehicle, repair costs, and the coverages, limits, and deductibles selected. Its recent rate-change guidance also discusses accidents, violations, claims, credit-related information, additional drivers, mileage changes, vehicle changes, and broader cost pressures.
For the carrier’s own explanation of why premiums move, review the Liberty Mutual rate-change guide. Use it as a reference, then compare your actual quote or renewal because individual underwriting, state rules, coverage, and policy details still matter.
If you want the broader carrier view before auditing the price, compare a Liberty Mutual insurance quote using one locked coverage baseline. This page is for the next step: figuring out which input actually moved the number.
Liberty Mutual Auto Insurance Rates: Driver and Claims History
Liberty Mutual auto insurance rates can move when the driver profile changes. Accidents, claims, speeding violations, more serious driving violations, and adding another driver can affect the premium. The effect is not one universal percentage because state rating rules, prior history, policy structure, severity, and other factors can change the result.
Liberty Mutual insurance rates after accident claims should therefore be checked against the previous declarations or quote. Compare the same vehicle, limits, deductibles, drivers, and effective date. If several things changed at renewal, it is easy to blame the accident for a price increase that also reflects a new car, mileage update, lost discount, or broader rate change.
Liberty Mutual insurance rates by age are also better understood as part of the full driver profile. Age, driving experience, household composition, state rules, and who actually operates the vehicle can overlap. A younger or newly added driver may affect the policy differently from an experienced driver with a long clean history.
Review recent losses, fault, severity, prior claims, and whether the claim period overlaps another driver or vehicle change.
Speeding, reckless driving, DUI-related history, and other violations can affect how the driver is rated.
A teen, newly licensed household member, or other regular driver can change the risk profile of the whole policy.
When reviewing a change, compare prior-policy information and make sure the application still reflects the real household.
Vehicle, Mileage, and Liberty Mutual Car Insurance Rates
Liberty Mutual car insurance rates can change with the vehicle itself. Liberty Mutual notes that make and model can influence premiums because theft exposure, repair costs, parts prices, engine performance, safety features, and crash characteristics differ. Two people with the same driving record can still receive different prices because the cars are not equally costly to repair or replace.
Liberty Mutual auto insurance cost can also change when annual mileage changes. More time on the road generally means more exposure to a possible crash. Keep commute, annual mileage, business use, and pleasure-use information accurate when you compare quotes.
Liberty Mutual car insurance cost is therefore not a fixed company-wide price. If you replace an older vehicle with a newer or more expensive model, change how far you drive, add a daily commute, or alter physical-damage coverage, the quote can move even if your driving record stays identical.
Liberty Mutual Rates by ZIP Code and Credit-Related Factors
Liberty Mutual rates by ZIP code should be tested with the ZIP where the vehicle is principally garaged. Location can reflect state insurance rules, local traffic, claim frequency, theft, weather exposure, repair costs, and other geographic risk. A move can change the quote even when the driver and vehicle remain the same.
Liberty Mutual car insurance cost by ZIP code is only meaningful when the rest of the quote stays constant. Keep the same drivers, vehicle, annual mileage, liability limits, collision and comprehensive choices, deductibles, effective date, and optional coverages. Otherwise, you are comparing two different insurance setups.
Liberty Mutual insurance rates by credit score are state-sensitive. Liberty Mutual explains that insurers may use a credit-based insurance score in many states, while some states prohibit or restrict use of credit information. This means a credit-related pricing effect should never be treated as a universal nationwide rule.
For another ZIP-based way to test the same inputs, compare auto insurance rates and costs by ZIP code. Keep the same limits and deductibles so the second-site comparison measures location and pricing rather than a weaker coverage setup.
Liberty Mutual Deductible Cost and Coverage Limit Changes
Liberty Mutual deductible cost should be viewed as a tradeoff between premium and claim-day cash exposure. Liberty Mutual explains that a higher auto deductible generally lowers premium, while a lower deductible generally raises premium but reduces what you may need to pay out of pocket after a covered loss.
Liberty Mutual coverage limits cost should be tested separately. Higher liability or property limits can increase the premium because the policy is providing more potential protection. If a quote becomes much cheaper after you edit it, verify that the price did not fall because a limit dropped or a coverage was removed.
| Quote change | Possible premium effect | What to verify |
|---|---|---|
| Higher collision deductible | Premium may decrease. | Confirm you could pay the larger deductible immediately after a covered collision. |
| Lower collision deductible | Premium may increase. | Compare the extra premium with the reduced out-of-pocket risk. |
| Higher liability limits | Premium may increase. | Judge the additional protection rather than treating the lowest legal limit as automatically better value. |
| Added optional coverage | Premium may increase. | Check whether the feature solves a real claim-day need before removing it only to lower the quote. |
RightTrack and Discounts: Price Modifiers, Not Base Factors
Liberty Mutual insurance cost can also change because a discount or driving program changes the final premium after the base quote is built. That is a different mechanism from changing the ZIP, driver, vehicle, mileage, limit, or deductible.
Liberty Mutual currently says RightTrack offers an initial participation discount and can produce savings of up to 30% for safe driving, depending on the program and state. Its current RightTrack information also says riskier driving behavior can result in a premium increase, and continuous-program scores can be reviewed at renewal. Treat RightTrack as a pricing modifier that belongs on top of a stable quote baseline.
If your main goal is how to lower Liberty Mutual insurance rates through bundling, RightTrack, payment choices, paperless options, or other discounts, use the dedicated savings page. Use that guide to verify savings before comparing the completed premium with matched coverage.
Liberty Mutual Home Insurance Rates: Replacement Cost Matters
Liberty Mutual home insurance rates are built from a different risk profile than auto insurance. Liberty Mutual currently highlights location, estimated replacement cost, age and condition, safety devices, and deductible among major factors that can affect homeowners pricing.
Estimated replacement cost is especially important because it is not the same as market value or a tax assessment. It is intended to reflect what rebuilding the structure could cost, including labor, materials, inflation, and local availability. Changing the dwelling amount can therefore change Liberty Mutual homeowners insurance cost without any change to the address itself.
Liberty Mutual home insurance cost can also reflect construction materials, age of the roof, renovations to home systems, weather exposure, claims history, coverage limits, and deductible choices. Avoid the old shortcut of assuming a specific roof age automatically produces one price result; the entire property profile matters.
Liberty Mutual home insurance quote factors should be saved before comparing a renewal or a second quote: property address, dwelling amount, construction type, roof details, occupancy, claims, safety devices, deductible, liability limit, and optional coverages.
Liberty Mutual home insurance rates by ZIP code should always use the real insured property location. Comparing two different addresses tells you how two risks are priced, not how one discount or deductible changed one home quote.
Why Did My Liberty Mutual Quote Change?
The search “why did my Liberty Mutual quote change” is best answered with a before-and-after audit. Compare the old quote with the new one and check the garaging ZIP, listed drivers, vehicle, mileage, claims, violations, credit-related information where permitted, coverage limits, deductibles, effective date, payment settings, discounts, and optional coverages.
The related question “why did my Liberty Mutual insurance rate go up” should be handled the same way at renewal. Liberty Mutual’s current educational material notes that rate changes can reflect personal factors such as accidents, claims, tickets, mileage, new drivers, credit-related information, and vehicle changes, while broader repair and claim costs can also affect pricing.
“Why is Liberty Mutual insurance so expensive” is not a useful conclusion until the quote is matched against another carrier with the same risk and protection. A high price can come from the driver, vehicle, ZIP, coverage, deductible, claim history, mileage, property details, or another rating input rather than from one universal Liberty Mutual rate.
If you want to rebuild the quote from the beginning, see how to get a Liberty Mutual quote online. If you need coverage to begin quickly for a vehicle purchase or renewal, you can also find same-day auto insurance coverage, but still verify the effective date and final policy details before relying on proof of insurance.
How to Compare Liberty Mutual Insurance Cost Without False Savings
Start with one control quote. Save the full policy-term premium, payment plan, drivers, vehicle, ZIP, annual mileage, liability limits, collision and comprehensive status, deductibles, add-ons, and discounts. For home, save the dwelling amount and property assumptions as well.
Then test one variable. If the price falls after you raise a deductible, you know the savings came with more out-of-pocket exposure. If the price changes after a move, the location changed. If the same coverage becomes cheaper after a discount is applied, that is a cleaner measure of the discount effect.
This method is the safest way to interpret Liberty Mutual insurance rates because it prevents a lower displayed number from hiding a weaker setup. Price matters, but the comparison is only valid when the protection remains intentional.
Liberty Mutual Insurance Rate FAQ
Liberty Mutual says auto pricing can reflect where you live, driving record, mileage, the vehicle you drive, repair costs, coverage choices, limits, deductibles, credit-related information where permitted, and other rating factors. Home pricing can reflect location, rebuild cost, age and condition, safety devices, deductible, claims history, and selected coverage.
A quote can change when a driver, vehicle, annual mileage, garaging ZIP, claims or violation history, coverage limit, deductible, effective date, payment setup, discount, or other application detail changes. Compare the old and new quote line by line and change only one input at a time when testing price.
Yes. Liberty Mutual identifies location as a factor in auto pricing. Use the ZIP where the vehicle is principally garaged and keep the remaining driver, vehicle, mileage, limits, and deductibles unchanged when you compare rates by location.
Accidents and claims can affect auto pricing, but the result is not one universal percentage. Fault, severity, prior history, state rules, policy changes, discounts, and other rating factors can affect what happens at the next quote or renewal.
In many states, insurers may use credit-related insurance information when setting auto or home rates. Liberty Mutual notes that state rules differ, so the effect is not uniform nationwide and some states prohibit or restrict the use of credit.
Liberty Mutual explains that choosing a higher auto deductible generally lowers premium while increasing what you may pay out of pocket after a covered claim. Home deductibles create a similar price-versus-claim-cost tradeoff.
Yes. Liberty Mutual says RightTrack can provide a participation discount and that the driving score may affect premium at renewal. Depending on the program, participation, driving behavior, risk factors, and state availability, the result can be a decrease or an increase.
Liberty Mutual highlights location, estimated replacement cost, age and condition, safety devices, and deductible as major home-pricing factors. Its homeowners materials also note claims history, coverage limits, construction details, weather exposure, and other property information.
Keep the same ZIP, drivers, vehicle, mileage, liability limits, comprehensive and collision choices, deductibles, effective date, and optional coverages. For home insurance, also keep the dwelling amount, property details, roof information, and deductible structure consistent.
Start by checking rating inputs for accuracy, then review deductibles you could actually afford, available discounts, bundling, mileage, and programs such as RightTrack where appropriate. Compare each change against the same baseline so a lower price is not simply the result of reduced coverage.
Bottom line: Liberty Mutual quote price factors become much easier to interpret when you stop changing several inputs at once. Lock the driver, vehicle, ZIP, mileage, limits, deductibles, and home assumptions first; then test one factor or discount at a time and judge the final premium against the protection you would actually keep.